Hydrogen Production and Uses
- Hydrogen is increasingly seen as a key component of future energy systems if it can be made without carbon dioxide emissions.
- It is starting to be used as a transport fuel, despite the need for high-pressure containment.
- Hydrogen is widely used in producing liquid transport fuels from crude oil, and is vital where tar sands are the oil source.
- Hydrogen can be combined with carbon dioxide to make methanol or dimethyl ether (DME) which are important transport fuels.
- Hydrogen also has future application as industrial-scale replacement for coke in steelmaking and other metallurgical processes.
- Nuclear energy can be used to make hydrogen electrolytically, and in the future high-temperature reactors are likely to be used to make it thermochemically.
Hydrogen is rarely found in free form (H2). Almost all the hydrogen used today is made by liberating it from molecules such as water or methane, using energy. Such hydrogen is therefore not a primary energy source. It is already a significant chemical product, used mainly in oil refining and in making ammonia for nitrogen fertilizers via the Haber process. There is a lot of experience handling hydrogen on a large scale, though it is not as straightforward as natural gas.
Most hydrogen today is made by steam reforming of natural gas or coal gasification, both with carbon dioxide (CO2) emissions. Future demand will be mainly for zero-carbon hydrogen. Plans for increased hydrogen production are essentially based on electrolysis using electricity from intermittent renewable sources. Off-peak capacity of conventional nuclear reactors or other power plants can also be used. In future, a major possibility for zero-carbon hydrogen production is decomposition of water by direct use of heat from nuclear energy, using a thermochemical process enabled by high-temperature reactors.
The demand for hydrogen by oil refineries and chemical plants favours technologies with low costs. Limited hydrogen pipeline networks already exist, allowing production facilities to be some way from users.
Like electricity, hydrogen is an energy carrier (but not a primary energy source). Hydrogen has some potential to replace oil as a transport fuel and in other applications. It is the preferred fuel for fuel cell electric vehicles (FCEVs), though portable storage at vehicle scale is a challenge. Hydrogen can also be used in internal combustion engines.
While hydrogen can replace liquid hydrocarbons, it is never as energy-dense or convenient to store and transport. However, it does compare well with batteries, which is why it and hydrogen-based liquid fuels have a lot of potential.
Electricity and hydrogen are convertible one to the other as energy carriers. However, the overall efficiency of electricity-hydrogen-fuel cell-electricity is no more than 40%. One approach to mitigate intermittency of wind and solar electricity is to make hydrogen by electrolysis and feed this into the gas grid, the power-to-gas strategy.
In future some hydrogen produced for fuel may be converted into ammonia as a more energy-dense carrier medium volumetrically for trade or long-term energy storage. The mass energy density of hydrogen is 120 or 142 MJ/kg*, compared with methane 50 MJ/kg, propane 46 MJ/kg and ammonia 19 MJ/kg. Volumetrically, the energy density of hydrogen is low – 10.8 or 12.75 MJ/Nm3 (or as liquid: 8.5 or 10.0 MJ/L)**. Ammonia is the main hydrogen derivative in consideration for transport.
* Lower (net heat of combustion) and higher (gross heat of combustion) heating values, respectively. Thus 33.3 or 39.4 kWh/kg. The higher heating value includes the latent heat in the vaporized water, the lower heating value (or net calorific value) excludes this.
** Nm3 = normal cubic metre (0 °C temperature and 1.01325 bar (i.e. 1 atmosphere) pressure.
The role of nuclear power
Nuclear power already produces electricity as a major energy carrier with well-known applications. Operating at very high capacity factors, nuclear energy is well placed to produce zero-carbon hydrogen as an emerging energy carrier with a wide range of applications. The evolution of nuclear energy's role in hydrogen production over perhaps two decades is seen to be:
- Cold electrolysis of water, using off-peak capacity (needs 50-55 kWh/kg).
- Low-temperature steam electrolysis, using heat and electricity from nuclear reactors.
- High-temperature steam electrolysis, using heat and electricity from nuclear reactors.
- High-temperature thermochemical production using nuclear heat.
In addition, nuclear heat can assist the process which provides most of the world's hydrogen today:
- Use of nuclear heat to assist steam reforming of natural gas (methane).
Steam reforming of methane (SMR) requires temperatures of over 700 °C to combine methane and steam to produce hydrogen and carbon monoxide. A nuclear heat source would reduce natural gas consumption by about 30% (i.e. that portion of feed which would simply be for heat), and eliminate flue gas CO2 emissions.
Starting with electrolysis, the efficiency of the whole process (primary heat to hydrogen) moves from about 25% with today's reactors driving electrolysis (33% for reactor x 75% for cell) to 36% with more efficient reactors doing so, to 45% for high-temperature electrolysis of steam, to about 50% or more with direct thermochemical production.
Hydrogen was first produced at the Kola plant in Russia in December 2022. Alkaline and proton exchange membrane (PEM) technology is employed.
Electrolysis at ambient temperature is being undertaken in at least four US projects at nuclear power plants. In August 2021 Nel Hydrogen was contracted to build a 1.25 MW PEM electrolyser at Exelon’s Nine Mile Point nuclear power plant to show integrated production, storage and normal use at the plant. Hydrogen production began there in March 2023, under the plant’s new owner Constellation.
Low-temperature steam electrolysis improves the efficiency of electrolysis at ambient temperatures and utilizes waste heat at up to 200 °C from a conventional reactor. The US Department of Energy (DOE) in October 2020 selected two projects to advance flexible operation of light water reactors with integrated hydrogen production systems to receive cost-shared funding. Two other projects were already under way.
High-temperature steam electrolysis (HTSE, at 550-750 °C or more) in solid oxide electrolysis cells (SOEC) to use both heat and electricity has been demonstrated, and shows considerable promise. It is a reverse reaction of the solid oxide fuel cell technology. It requires about one-third less electricity than low-temperature electrolysis but its commercialization has been held back by the poor durability of the ceramic components in a hot hydrogen environment. Solid oxide electrolysers are now made commercially, for example by Bloom Energy and Topsoe. One of the four DOE projects mentioned above will focus on a solid oxide electrolysis cell at high temperature. Idaho National Laboratory will work with Xcel Energy to demonstrate HTSE technology using heat and electricity from one of Xcel Energy’s nuclear plants.
The International Atomic Energy Agency (IAEA) has developed the Hydrogen Economic Evaluation Program (HEEP) to assess the economics of large-scale hydrogen production using nuclear energy.
Nuclear hybrid energy systems for hydrogen production
| Alkaline electrolysis | PEM electrolysis | Solid oxide electrolysis | Steam methane reforming | Thermochemical S-I | |
|---|---|---|---|---|---|
| Technology readiness | 9 | 6-8 | 5 | 9 | 4 |
| Temperature (°C) | 60 | 60 | 800 | 870 | 910 |
| Pressure (atm) | 1 | 1 | 1.57 | 4.1 | 3.85 |
| Efficiency (HHV, %) | 30 | 27 | 36 | 79 | 25 |
| Electricity (MJ) | 180 | 200 | 146 | 1.4 | 75 |
| Heat (MJ) | 26 | 26 | 30 | 0 | 375 |
| Water (kg) | 11.5 | 11.5 | 83 | 10.3 | 9 |
| Natural gas (kg) | 0 | 0 | 0 | 2.9 | 0 |
| CO2 out (kg) | 0 | 0 | 0 | 5-11 | 0 |
| Production cost | $5.92 | $3.56-5.46 | $2.24-3.73 | $1.54-2.30 | $2.18-5.65 |
Efficiency assumes 40% heat to electricity conversion
Source: Pinsky et al. 2020, Table 4
Hydrogen directly from nuclear heat
Several direct thermochemical processes are being developed for producing hydrogen from water. For economic production, high temperatures are required to ensure rapid throughput and high conversion efficiencies. They essentially do not use electricity.
In each of the leading thermochemical processes the high-temperature (800-1000 °C), low-pressure endothermic (heat absorbing) decomposition of sulfuric acid produces oxygen and sulfur dioxide:
2H2SO4 ⇒ 2H2O + 2SO2 + O2
There are then several possibilities. In the iodine-sulfur (I-S) process invented by General Atomics in the 1970s, iodine combines with the sulfur dioxide and water to produce hydrogen iodide. This is the Bunsen reaction and is exothermic, occurring at low temperature (120 °C):
I2 + SO2 + 2H2O ⇌ 2HI + H2SO4
The HI then dissociates to hydrogen and iodine at about 350-450°C, endothermically:
2HI ⇌ H2 + I2
This can deliver hydrogen at high pressure.
Combining all this, the net reaction is then:
2H2O ⇒ 2H2 + O2
All the reagents other than water are recycled, there are no effluents, hence it may be called the sulfur-iodine cycle, with zero-carbon hydrogen and oxygen byproducts.
In February 2010 the Japan Atomic Energy Agency (JAEA) set up the HTGR Hydrogen and Heat Application Research Centre at Oarai to progress operational technology for an I-S plant to make hydrogen thermochemically. It has demonstrated laboratory-scale and bench-scale hydrogen production with the I-S process, up to 30 litres/h. In parallel with JAEA’s High Temperature Engineering Test Reactor (HTTR) developments, a pilot plant test project producing hydrogen at 30 m3/h from helium heated with 400 kW tested the engineering feasibility of the I-S process. An I-S plant producing 1000 m3/h (90 kg/h, 2 t/day) of hydrogen was to be linked to the HTTR to confirm the performance of an integrated production system, envisaged for the 2020s. In January 2019 it produced hydrogen continuously for 150 hours using the iodine-sulfur process, in a test facility built from industrial materials. JAEA aims to produce hydrogen at less than $3/kg by about 2030 with very high temperature reactors. In March 2025 JAEA applied to the Nuclear Regulation Authority for approval to connect a hydrogen production facility to the HTTR.
The US Nuclear Energy Research Initiative (NERI) launched in 1999 was refocused in 2004 to include the Nuclear Hydrogen Initiative (NHI), allied to the Next Generation Nuclear Plant (NGNP) programme established in 2005. NGNP envisaged construction and operation of a prototype high-temperature gas-cooled reactor (HTR) and associated electricity or hydrogen production facilities by 2021, but funding was cut back under the Obama administration and prelicensing activities were suspended in 2013.
Under an international NERI agreement, Sandia National Laboratories in the USA and the French CEA with General Atomics in the USA were also developing the I-S process with a view to using high-temperature reactors for it. They had built and operated a laboratory-scale loop for thermochemical water-splitting.
South Korea has also demonstrated thermochemical water-splitting at laboratory scale, supported by General Atomics. In December 2008, the Korea Atomic Energy Commission officially approved nuclear hydrogen development as a national programme, with the development of key and basic technologies through 2017 and the goal of demonstrating nuclear hydrogen production using the I-S process and a very high-temperature reactor (VHTR) by 2026.
In June 2026 India inaugurated a facility at the Indira Gandhi Centre for Atomic Research in Kalpakkam that produces hydrogen using process heat from the Fast Breeder Test Reactor. It uses the copper-chlorine thermochemical cycle developed by the Bhabha Atomic Research Centre.
The economics of hydrogen production depend on the efficiency of the method used. The I-S cycle coupled to a modular high-temperature reactor is expected to produce hydrogen at about $2.00/kg. The oxygen byproduct also has value. General Atomics earlier projected $1.53/kg based on a 2400 MWt HTR operating at 850 °C with 42% overall efficiency, and $1.42/kg at 950 °C and 52% efficiency (both 10.5% discount rate). Such a plant could produce 800 tonnes of hydrogen per day.
Production reactor requirements for process heat
For thermochemical hydrogen production, high temperature – 750-1000 °C – is required, and at 1000 °C the conversion efficiency is three times that at 750 °C. The chemical plant needs to be isolated from the nearby reactor, for safety reasons, possibly using an intermediate helium or molten fluoride salt loop.
Three potentially-suitable nuclear reactor concepts have been identified, though only the first is sufficiently well-developed to move forward with:
- High-temperature gas-cooled reactor (HTR), either the pebble bed or hexagonal fuel block type. Modules of up to 600 MWt will operate at 950 °C.
- Advanced high-temperature reactor (AHTR), a modular reactor using a coated-particle graphite-matrix fuel and with molten fluoride salt as primary coolant. This is similar to the HTR but operates at low pressure (less than 1 atmosphere) and higher temperature, and gives better heat transfer. Sizes of 1000 MWe/2000 MWt are envisaged.
- Lead-cooled fast reactor, though these operate at lower temperatures than HTRs – the most developed is the Russian BREST reactor which runs at only 540 °C and is now under construction.
These are described more fully in the Small Nuclear Power Reactors information page (with coolant characteristics) and the Advanced Nuclear Power Reactors page.
For temperatures beyond 750 ºC, molten fluoride salts are a preferred interface fluid between the nuclear heat source and the chemical plant. The aluminium smelting industry provides substantial experience in managing them safely. The hot molten salt can also be used with secondary helium coolant generating power via the Brayton cycle, with thermal efficiencies of 48% at 750 °C to 59% at 1000 °C. There remain significant challenges in achieving sustained temperatures for commercial hydrogen production in a plant built for these chemical and thermal conditions.
National and regional plans and projections for hydrogen
Global hydrogen demand passed 100 Mt for the first time in 2025, almost all of it for traditional uses in industry and refining. Low-emissions hydrogen production reached almost 1 Mt, less than 1% of total output.
The International Energy Agency (IEA), in its World Energy Outlook 2025, projects annual low-emissions hydrogen production of 123 Mt in 2035 and 376 Mt in 2050 under its Net Zero Emissions by 2050 Scenario. Of the 2050 output, 304 Mt is produced by electrolysis and 71 Mt from fossil fuels with carbon capture, utilization and storage (CCUS). Achieving this pathway would require substantial additional policy action. The IEA’s Global Hydrogen Review 2026 identifies $41 billion in public funding in hydrogen policy updates since its 2025 review. Capital spending on low-emissions hydrogen projects reached nearly $7 billion in 2025. Access to low-cost clean electricity remains a key requirement for competitive hydrogen production by electrolysis.
Low-emissions hydrogen can help decarbonize those sectors which are hard or expensive to directly electrify, such as steel production and shipping.
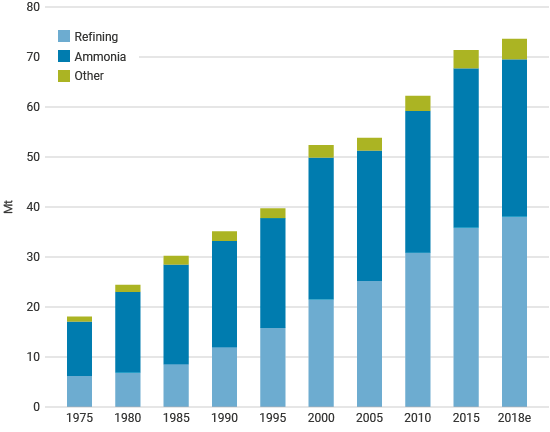
Figure 1: Global annual demand for pure hydrogen, 1975-2018 (source: IEA, The Future of Hydrogen, 2019)
'Green hydrogen' is produced by electricity from intermittent renewables.
'Grey hydrogen' is that produced from methane with corresponding CO2 emissions.
'Brown hydrogen' is produced from gasified coal, with CO2 emissions.
'Blue hydrogen' is grey or brown hydrogen but with carbon capture and storage (typically 50-70% efficient).
'Yellow hydrogen' or 'pink hydrogen' uses nuclear electricity for electrolysis and possibly heat.
'Turquoise hydrogen' is produced by molten metal pyrolysis of methane, with solid carbon byproduct.
Only green and yellow hydrogen are reliably zero-carbon. Future thermochemical production from nuclear power does not yet have a name. Green hydrogen may be from surplus supply to grids, or with dedicated supply capacity giving more economical utilization of electrolyser capacity (though it can never be greater than the capacity factor of the supply).
A database of hydrogen projects worldwide is provided by the International Energy Agency.
In Europe, EU energy ministers signed the Hydrogen Initiative, a non-binding political declaration of support for hydrogen development, in September 2018. The EU has launched a large ‘green hydrogen’ programme based on surplus power from intermittent renewables sources to decarbonize industry and aviation and to develop export opportunities. Green hydrogen is seen as key to reaching 'net-zero' emissions targets, but as yet, costs are high due to expensive equipment and the amount of electricity required.
The EC’s hydrogen strategy for the EU published in July 2020 called for the installation of at least 6 GWe of electrolysers powered by renewable energy by 2024. Its objective for 2030 was at least 40 GWe, producing up to ten million tonnes of renewable hydrogen per year. Installed electrolyser capacity in the EU reached about 308 MW in 2024.
The REPowerEU plan of May 2022 added a target of 10 Mt per year of renewable hydrogen imports by 2030. In 2024 the European Court of Auditors reported that the EU was unlikely to meet its 2030 renewable hydrogen targets.
In February 2023 nine nations led by France – including Poland, the Czech Republic, Romania, Bulgaria, Slovenia, Croatia, Slovakia, and Hungary – called for the EC to recognize hydrogen production from nuclear as a green energy source. The same month, the EC published a set of draft rules that could allow some hydrogen produced from nuclear to count towards EU renewable energy targets. The rules were formally published in June 2023 and entered into force the following month. Under them, electricity from a grid with low emissions intensity counts as renewable only where the hydrogen producer also holds renewable power purchase agreements. A separate regulation defining low-carbon hydrogen was adopted in July 2025. It requires the Commission to assess, by July 2028, a pathway for low-carbon electricity from nuclear power plants.
Germany’s national hydrogen strategy approved in June 2020 offered about €7 billion to bring electrolyser capacity to 5 GW by 2030 for 14 TWh of green hydrogen requiring 20 TWh of renewable electricity. The July 2023 update of the strategy doubled the 2030 electrolyser target to 10 GW. In autumn 2025 the economy ministry said it would scrap the 10 GW target in favour of a more flexible approach. The strategy also provided €2 billion for projects abroad, as hydrogen imports will be needed – only a small proportion of estimated 2030 demand will be produced domestically. While the objective is to use green hydrogen, both blue and turquoise hydrogen will play a part.
France committed €7 billion for green hydrogen from 6.5 GW electrolyser capacity by 2030, with €2 billion of this over the two years to 2022, in support of its 2018 hydrogen strategy. Some 40% of this was to be funded from the EU’s €750 billion coronavirus recovery programme. The revised national hydrogen strategy published in April 2025 cut the 2030 target to up to 4.5 GW and set a target of 8 GW for 2035.
Spain's government has approved a 2030 hydrogen roadmap targeting the installation of 4 GW of electrolysis capacity, green hydrogen quotas for industrial consumers, and the use of hydrogen in transport among other measures aligned with the EU hydrogen strategy. The updated National Energy and Climate Plan approved in September 2024 raised the 2030 target to 12 GW. Spain now produces and uses 0.5 million tonnes per year of hydrogen.
Netherlands' hydrogen strategy aimed for 500 MW of electrolysers by 2025 and 3-4 GW by 2030. Installed capacity reached only about 7 MW in 2024. In September 2025 the government put back the 3-4 GW target to 2035.
The UK's strategy around hydrogen production considers carbon intensity as the primary factor in market development, aiming to be low-carbon. The UK Hydrogen Strategy published in August 2021 aims to decarbonize transport and industry, using both green and blue hydrogen. It projects 5 GW of low-carbon hydrogen production capacity by 2030, mainly blue hydrogen, to produce one-fifth of the 2050 target. The British Energy Security Strategy of April 2022 doubled this ambition to up to 10 GW, with at least half from green hydrogen. In December 2023 the first hydrogen allocation round selected 11 projects totalling 125 MW for support.
In Slovakia a national hydrogen strategy adopted in April 2021 envisages production from nuclear power by electrolysis.
China is the world’s largest hydrogen producer. Most of China’s hydrogen production, which exceeded 39 million tonnes a year in 2026, is from coal. In March 2022 the government published its first medium- and long-term plan for the hydrogen industry, covering 2021 to 2035.
Japan’s Ministry of Economy, Trade and Industry (METI) produced a comprehensive hydrogen strategy roadmap in 2016 and updated it in 2019. It aims to reduce the cost to JPY 30/Nm3 by 2030, and to ¥20 later. Japan plans to import zero-carbon hydrogen and ammonia. METI’s December 2020 Green Growth Strategy Through Achieving Carbon Neutrality in 2050 aims for hydrogen and ammonia fuelling 10% of power generation as well as providing energy for shipping and steelmaking. A revision of the Basic Hydrogen Strategy in June 2023 set supply targets, including ammonia, of 3 Mt per year by 2030, 12 Mt by 2040 and 20 Mt by 2050. The Hydrogen Society Promotion Act, enacted in May 2024, offers 15 years of price-gap support to suppliers of low-carbon hydrogen.
In March 2020 METI's New International Resource Strategy identified ammonia as a promising means of “importing renewable energy produced in other countries.” In October 2020 METI set up the Ammonia Energy Council with major companies from the private sector and aiming to position Japan as a global leader in ammonia as an energy source, especially in power stations and marine transport, via dissemination of technology and development of supply chains.
South Korea has plans for increasing use of FCEVs, especially buses and trucks fuelled by zero-carbon hydrogen, and expects hydrogen demand to double by 2030. Its national hydrogen roadmap says: “The total potential of hydrogen in Korea amounts to 17 Mt (equivalent to 564 TWh) in 2050, accounting for more than 20% of total national energy demand.” This is mainly blue hydrogen.
Russia adopted a concept for the development of hydrogen energy in August 2021. Gazprom was to test a new hydrogen turbine in 2021, and a partnership between Gazprom Energieholding and Siemens was reported to be pending. Gazprom aims to produce turquoise hydrogen by pyrolysis of methane (rather than steam reforming) to leave solid carbon rather than CO2. Rosatom produced hydrogen for the first time in December 2022 at the 1,760-MW Kola nuclear power plant and is planning to increase it to 10 MW as a demonstration project for wider adoption.
In April 2021 Rosatom announced plans with Gazprom to produce hydrogen on the island of Sakhalin using steam methane reforming with CCS. It agreed to supply fuel for hydrogen-powered trains there and envisaged possible exports to Japan and South Korea. After a pause, Rosatom said in July 2026 that work on the project had resumed. Its potential production is put at 36,500-100,000 tonnes per year.
In the USA, the Department of Energy’s (DOE's) H2@Scale initiative supports innovations to produce, store, transport, and utilize hydrogen across multiple sectors. The USA produces about 10 Mt of hydrogen per year, mainly for petroleum refining and ammonia production.
In November 2020 the DOE released its Hydrogen Program Plan to provide a strategic framework for its hydrogen research, development, and demonstration (RD&D) activities. The DOE’s National Clean Hydrogen Strategy and Roadmap, published in June 2023, targets clean hydrogen production of 10 Mt per year by 2030, 20 Mt by 2040 and 50 Mt by 2050.
Final rules for the US clean hydrogen production tax credit, published in January 2025, allow some existing nuclear plants to qualify. Legislation enacted in July 2025 limits the credit to facilities that begin construction before 2028. In October 2023 the DOE selected seven regional clean hydrogen hubs to receive up to $7 billion in funding, subject to negotiation. In October 2025 it terminated funding for two of them, in California and the Pacific Northwest.
In Australia, gasification of lignite in Victoria’s Latrobe Valley is planned in the National Hydrogen Roadmap, eventually with CCS in the nearby Gippsland Basin. The Hydrogen Energy Supply Chain project began producing hydrogen in the Latrobe Valley in January 2021, in an A$500 million pilot. The hydrogen was taken by road to Hastings and liquefied. The first shipment reached Kobe in Japan in February 2022, completing the pilot. Dismantling of the pilot production plant was scheduled to begin in September 2025.
Hydrogen production
Almost all hydrogen today is made from carbon-based materials, with significant CO2 emissions. A small amount is made by electrolysis of water.
As well as the financial cost, the energy cost is significant. Input energy exceeds the energy content of the hydrogen output by a factor of at least 1.5.
Steam methane reforming, coal gasification
Most hydrogen today is made by steam reforming of natural gas (methane, hence ‘SMR’). About one-quarter of supply is from coal, by reacting it with steam and oxygen under high temperature and pressure to form synthesis gas comprising hydrogen with carbon monoxide. These produce so-called grey hydrogen, unless the CO2 emissions are substantially mitigated by carbon capture and storage (CCS) in which case it is blue hydrogen.
In steam-methane reforming, methane reacts with steam under 3-25 bar pressure in the presence of a catalyst to produce hydrogen and carbon monoxide (with a small amount of carbon dioxide). Steam reforming is endothermic and uses steam at 700 °C to 1000 °C.
CH4 + H2O ⇌ CO + 3H2 ∆H +206 kJ/mol
CO + H2O ⇌ CO2 + H2 ∆H -41 kJ/mol – water-gas shift reaction (exothermic)
Coal gasification is similar, reacting carbon in coal with oxygen and steam under high temperature and pressure:
3C + O2 + H2O ⇌ 3CO + H2
CO + H2O ⇌ CO2 + H2 ∆H -41 kJ/mol – water-gas shift reaction (exothermic)
With about 76% of pure hydrogen being made from natural gas and 23% from coal gasification, this gave rise to 830 Mt of CO2 emissions in 2018 – each tonne of hydrogen produced by SMR gives rise to at least 11 tonnes of CO2.
The Great Plains Synfuel plant in the USA produces 1300 tonnes of hydrogen per day in the form of hydrogen-rich syngas from brown coal gasification, with CCS. About half of the CO2 is captured and sold to two oilfields for enhanced oil recovery.
Air Products at Port Arthur, Texas, employs SMR using vacuum-swing adsorption gas separation technology (rather than amine absorption) for carbon capture from 2013. It captures about 90% of the CO2 and sells about 1 Mt/yr for enhanced oil recovery nearby. The US Department of Energy (DOE) funded two-thirds of the cost of the project.
At the Quest project in Alberta, Canada, hydrogen is produced by SMR and an unknown proportion of the CO2 – up to 1 Mt/yr – is stored 2 km underground.
Australian plans for gasification of lignite envisage plants of over 500 t/day to be economical, hence relying on exports to achieve scale.
Pyrolysis
So-called turquoise hydrogen can be made by pyrolysis decomposition of methane, using a molten metal reactor with a catalytic active Ni-Bi alloy, leaving a solid carbon residue. The process heat can be from burning hydrogen product or methane, or electric arc. Alternatively a plasma reactor may be used.
CH4 -> C + 2H2 (endothermic)
Electrolysis
Electrolysis of water at ambient temperatures requires 50-55 kWh per kilogram of hydrogen produced* (hence 60% and potentially 70% efficient with improved catalysts). It also requires 9 litres of water for every kilogram produced. Electrolysis is undertaken on a fairly small scale today. In June 2023 Sinopec started production at an electrolysis plant at Kuqa in Xinjiang, China, designed to produce 20,000 tonnes of hydrogen per year.
Installed electrolysis capacity worldwide doubled in 2025 to more than 4 GW, according to the IEA. China accounted for nearly three-quarters of the new installations.
The main technology considered – proton exchange membrane (PEM) electrolysis – requires high-purity water, so electrolysers need an integrated deionizer allowing them to use fairly low-grade potable water.
* The thermodynamic efficiency limit is 40 kWh/kg, and 45 kWh/kg is considered the likely best achievable. Nevertheless Rolls-Royce suggests a yield of 87,000 t hydrogen per year from electrolysis using its UK SMR producing 3.5 TWh/yr.
There are three main types of electrolyser: alkaline (AE), polymer electrolyte membrane also known as proton exchange membrane (PEM), and solid oxide.
- Alkaline, using potassium hydroxide, is the most mature technology and is widely used in fertilizer and chlorine industries, but has some limitations. Most large-scale hydrogen production by electrolysis is using alkaline electrolysers (AE). Needs 50 kWh/kg hydrogen.
- PEM units use pure water and are relatively small but can be flexible in operation. They can also generate hydrogen at high pressure (30-60 bar, compared with alkaline 1-30 bar). However they use expensive electrode catalysts (platinum, iridium) and membrane materials and have short lifetimes. Needs 55 kWh/kg hydrogen.
- Solid oxide electrolysers use ceramic materials and operate at high temperatures. Very slow ramp time, less durable than other types. Needs 40 kWh/kg hydrogen.
An anion exchange membrane (AEM) type is being developed, with dilute alkaline electrolyte in 2.4 kW modules. Efficiency of 4.8 kWh/m3 hydrogen is claimed, with low costs.
Recent plans in several countries have focused on green hydrogen production by electrolysis. The plans for massively increased electrolyser deployment, fed by surplus electricity from renewables, are based on this. It would mean that increased deployment of intermittent renewables would result in less curtailment, and thus justify such overcapacity with low utilization (due to wind and solar intermittency). However, low capacity factors for the electrolysers would result in higher costs for the hydrogen.
High-temperature steam electrolysis based on solid oxide electrolysis cells (SOECs) requires about one-third less electricity but is at an early stage of commercialization. SOECs operate at over 600 °C (and are essentially solid oxide fuel cells run in regenerative mode). The solid oxide electrolyte is typically zirconia (zirconium dioxide, ZrO2). A source of heat such as nuclear would help commercialize SOECs and the IEA notes that nuclear power is ideally suited to this application.
The IEA points out that SOECs can be used in reverse mode as fuel cells to produce electricity and hence: "Combined with hydrogen storage facilities, they could provide balancing services to the power grid, increasing the overall rate of utilisation of equipment. SOEC electrolysers can also be used for co-electrolysis of steam and carbon dioxide, thereby creating a syngas mixture for subsequent conversion into synthetic fuel."
A 2.6 MW SOEC system started up at Neste’s Rotterdam refinery in October 2025. Several European companies are manufacturing SOEC systems. In Denmark, Topsoe opened a solid oxide electrolyser manufacturing plant at Herning in October 2025, with an initial capacity of 500 MW per year.
Since the hydrogen is able to be stored much more readily than electricity, this is an important potential application of surplus power from intermittent renewable sources, as well as for nuclear power especially off-peak. However, production from electrolysers is expensive.
The IEA's The Future of Hydrogen suggests that lowest hydrogen costs will be with 2500 or more full-load hours per year of electrolyser use. At less than this, capital expenses comprise a high proportion of cost.
Germany had 181 MW of electrolyser capacity in operation in early 2026.
Shell’s 10 MW PEM electrolyser at its Rhineland refinery started operating in July 2021. Shell took a final investment decision on a 100 MW electrolyser at the same site in July 2024.
BP took a final investment decision in December 2024 on a 100 MW electrolyser at its Lingen refinery. RWE is building 300 MW of electrolysers at Lingen as part of the GET H2 Nukleus project. Hydrogen from its first two 100 MW units, then being commissioned, reached Marl in the Ruhr area in August 2026.
Siemens Smart Infrastructure and WUN H2 built a hydrogen production plant at Wunsiedel in northern Bavaria, next to an existing 8 MW battery unit. The plant started operation in September 2022. It uses a 'Silyzer 300' PEM electrolyser from Siemens Energy with 8.75 MW of capacity, powered solely by renewable energy. The plant can produce 1,350 t/yr of hydrogen. Siemens sees it as a demonstration plant.
In Norway, Nel opened a factory at Heroya in April 2022 to produce 500 MW of electrolysers per year, at about $500/kW. Its alkaline production lines there were idle in December 2025.
In Denmark, green hydrogen company Everfuel contracted Norway’s Nel to supply a 20 MW alkaline electrolyser to produce 8 tonnes per day of hydrogen from wind power. The plant, HySynergy at Fredericia, was inaugurated in November 2025.
The EDF Energy Hydrogen to Heysham (H2H) project in the UK demonstrated technical and commercial feasibility of producing hydrogen by electrolysis using electricity directly from nuclear with a heavily reduced carbon footprint. The report on the trial estimated that future electrolyser capacity of about 550 MW across EDF’s UK nuclear fleet could produce about 220 tonnes of hydrogen per day by 2035, with a levelized cost of hydrogen as low as £1.89/kg ($2.44/kg) depending on power price and falling technology costs over a 20-year project cycle.
Also in the UK, ITM Power opened a PEM electrolyser factory in Sheffield in August 2021.
In Spain, Iberdrola has built a 20 MW green hydrogen unit coupled to a 100 MW solar PV array and a 20 MWh battery system for €150 million at Puertollano for ammonia production.
In Japan a 10 MW electrolyser paired with 20 MWe of solar PV started operation in 2020.
In Saudi Arabia, an $8.4 billion project near Neom is designed to use 4 GWe of renewables to produce up to 600 tonnes per day of green hydrogen using Thyssenkrupp electrolysers and then green ammonia. Production of 1.2 Mt of ammonia per year for export would be from Topsoe technology (essentially Haber-Bosch). Construction was in its final stages in 2026, and commissioning had begun.
Hydrogen directly from nuclear heat
See section above under Role of Nuclear Power.
Hydrogen uses
Supplement in reticulated natural gas
In most pipelines, 15-20% hydrogen can be added to natural gas. One limitation is that hydrogen has only one-third the calorific value of methane by volume, hence boilers need modification to run on higher mixes of hydrogen than about 20%. Also hydrogen can cause embrittlement of steel.
In the UK, Project Union launched in March 2021 aims to repurpose around 25% of current gas transmission pipelines to carry “at least a quarter” of current British gas demand, according to National Grid.
Oil refining
Hydrogen is a key processing agent in petroleum refining, for desulfurizing and catalytic cracking of long-chain hydrocarbons.* It is also used to convert low-grade crude oils (especially those from tar sands) into liquid and energy-dense transport fuels such as gasoline and diesel fuel. Heavy aromatic feedstock is converted into lighter alkane hydrocarbon products under a wide range of very high pressures (7000-14,000 kPa) and high temperatures (400-800°C), utilizing hydrogen and special catalysts. It is also important for removing contaminants such as sulfur from these fuels.
* e.g. (CH)n tar sands or (CH1.5)n heavy crude to (CH2)n transport fuel about 42-45 MJ/kg (32-39 MJ/L). Upgrading heavy crude oil and tar sands requires 3 to 4 kilograms of hydrogen per barrel (159 litres) of product.
Production of ammonia
Synthesis of hydrogen and nitrogen to produce ammonia – about 180 Mt/yr or 1 PWh* – accounted for about 43% of the world's pure hydrogen demand in 2018. This uses the Haber-Bosch process.
* On the basis of 5.18 kWh/kg ammonia, quantities may be quoted in GWh, PWh, etc.
Most ammonia today is used for agricultural fertilizers. Some is used (as ammonium nitrate, with diesel fuel) for mining explosives. It may also be burned as transport fuel or cracked to yield hydrogen as fuel.
According to Norman Borlaug, 1970 Nobel laureate and 'grandfather of the green revolution', organic nitrogen in the world's soils is only sufficient to feed one-third of today's population. The rest must come from inorganic additions. Most of the world's nitrogen fertilizers are made using the Haber process (see below), combining hydrogen with abundant atmospheric nitrogen. The resulting ammonia is then oxidized to nitrates.
The Haber process
The Haber Process (Haber-Bosch Process) combines nitrogen from the air with hydrogen derived mainly from natural gas (methane) into ammonia. The reaction is reversible and the production of ammonia is exothermic.
German scientist Fritz Haber invented the process to combine atmospheric nitrogen with hydrogen in 1909 and received the Nobel Prize for chemistry in 1918 for creating "an exceedingly important means of improving the standards of agriculture and the well-being of mankind," which now looks like a considerable understatement. It was scaled up by the chemical engineer Karl Bosch, so is often known as the Haber-Bosch process. Bosch received a Nobel Prize in 1931.
N2 + 3H2 ⇌ 2NH3 ∆H -92 kJ/mol (exothermic, using a metal catalyst at high temperature and pressure)
The Haber process produces about 180 million tonnes of anhydrous ammonia per year for nitrogen fertilizers and consumes about 3-5% of the world's natural gas production to make the hydrogen for it. The nitrogen is obtained cryogenically from air.
Looking to the future, ammonia could have a key role in the storage and transport of hydrogen – see later section. It may also be used as a fuel. In Japan, JERA completed a trial co-firing 20% ammonia with coal in a 1 GW unit at its Hekinan power station in June 2024. Ammonia also has potential use as a maritime fuel, since it can be used in ship engines with only minor modification. Also it can be used in some fuel cells.
Production of methanol and DME fuels
Considering the storage and portability challenges of hydrogen itself, as well as the radical change to fuel cell cars, there is some use of methanol as an additive to petrol/gasoline. Any future liquid fuel for cars needs to compete with petrol at 32 MJ/L or diesel fuel at 39 MJ/L and be no more difficult to store and refuel than LPG. Methanol (CH3OH) has 16 MJ/L. It may be used in fuel cells.
LNG has similar problem to hydrogen, ethanol generally comes from biomass, but methanol can be made from CO2 and hydrogen. Using zero-carbon hydrogen, and with abundant CO2, automotive fuel can be provided forever, using present engine technology.
For diesel engines, dimethyl ether (CH3-O-CH3, DME) is better, and this is made by dehydrating a couple of methanol molecules. It is a gas but can be stored under low pressure as a liquid, like LPG. DME has an energy density of 18-19 MJ/L, so less than oil-based fuels, but usable and easily stored.
Methanol today is produced in a variety of ways, but ideally it will be produced from atmospheric CO2 with hydrogen produced by nuclear energy, and using more nuclear energy in the conversion process.
CO2 + 3H2 ⇒ CH3OH + H2O ∆H -49.5 kJ/mol at 25°C, -58 at 225°C, exothermic
(The endothermic reverse water shift reaction CO2 + H2 ⇒ CO + H2O will occur at same time, along with: CO + 2H2 ⇒ CH3OH ∆H -91 to -98 kJ/mol, exothermic)
Dimethyl ether is made in a dehydration reaction:
2CH3OH ⇒ CH3OCH3 + H2O ∆H -23 kJ/mol
Methanol and DME production is at relatively low temperature (compared with thermochemical hydrogen production) – 230-350°C.
DME is already used as propane replacement, and world production capacity is over 10 million tonnes per year.
Most methanol production today is from synthesis gas (carbon monoxide and hydrogen) derived from biomass or fossil fuels, or from hydrogen by steam reforming of natural gas. Most methanol use is for making plastics. About 14% of it is used as a petrol additive and 7% to make DME. Methanol production accounts for about 13% of the world’s hydrogen demand.
Ethanol production is covered in the Nuclear Process Heat for Industry information page.
Methanol, together with derived DME, can be used as:
- A convenient energy storage medium.
- A readily transportable and dispensable fuel for internal combustion engines and diesel (compression ignition) engines with little engineering change.
- As sustainable aviation fuel (SAF) for jet engines.
- A fuel for fuel cells.
- A feedstock for synthetic hydrocarbons and their products, including fuels, polymers and even single-cell proteins (for animal feed and/or human consumption).
In Iceland, methanol production is already occurring using CO2 captured from flue gas and hydrogen from electrolysis using renewable energy. The company Carbon Recycling International was set up in 2006 to produce renewable methanol for automotive use and also biodiesel.
In China, the Shanghai Advanced Research Institute has developed a process to convert CO2 and hydrogen into long-chain hydrocarbons such as in gasoline. A multifunctional catalyst containing indium oxide mixed with a zeolite initially produces methanol, which then interacts with the zeolite to produce long-chain hydrocarbons. Another research group at the Dalian Institute for Chemical Physics uses a magnetite and zeolite catalyst to also produce long-chain hydrocarbons from CO2 and hydrogen, but with different intermediate products. While there are a number of processes that can convert CO2 to single-carbon hydrocarbons such as methanol, the synthesis of longer-chain hydrocarbons has previously been elusive.
Hydrogen can also be reacted with carbon dioxide at 300-400°C to give methane, using the exothermic Sabatier process.*
* CO2 + 4H2 ⇒ CH4 + 2H2O. This seems of more relevance to space travel than transport on Earth, though on a small scale it will scrub CO2 and CO from hydrogen streams for fuel cells.
Use directly as fuel for land transport – fuel cells
Burning hydrogen produces water vapour, with no carbon dioxide or carbon monoxide, but burning it in air can produce nitrogen oxides. However, unless it is liquid it is far from being an energy-dense fuel volumetrically, and this limits its potential use, especially for light motor vehicles. There is more potential for trucks. Ammonia is more energy-dense, and burns to water vapour and NOx or nitrogen.
Hydrogen can be burned in a normal internal combustion engine, and some test cars were thus equipped. Trials in aircraft have also been carried out. Until about 2010 the internal combustion engine was the main affordable technology available for using hydrogen.*
*One hundred BMW Hydrogen 7s were built, and the cars covered more than 2 million kilometres in test programmes around the globe. BMW is the only car manufacturer to have used hydrogen stored in its liquid state. BMW has abandoned this development and is collaborating with Toyota on fuel cell vehicles.
For transport, hydrogen’s main use is in fuel cell electric vehicles (FCEVs). A fuel cell is conceptually a refuellable battery, making electricity as a direct product of a chemical reaction. But where the normal battery has all the active ingredients built in at the factory, fuel cells are supplied with fuel from an external source and oxygen from the air. They catalyse the oxidation of hydrogen directly to electricity ideally at relatively low temperatures.
Proton exchange membrane or polymer electrolyte membrane (PEM) fuel cells are the main type used in cars and heavy vehicles. These operate at around 80-90 °C with high volumetric power density and an acidic electrolyte. They have high volumetric power density and long life but require high-purity hydrogen and a noble metal catalyst – typically platinum, adding to cost. They have about 60% efficiency in converting chemical to electrical energy to drive the wheels of an electric vehicle though in practice about half that has been achieved.
Alkaline fuel cells (AFCs) operate at about 200 °C, are relatively well-developed and are above 60% efficient. NASA has used AFCs since the 1960s in Apollo missions and on the space shuttle (they also produce potable water). They are the least expensive to make, using non-noble metal catalysts, and can use less-pure hydrogen from cracking ammonia – but poisoning by CO2 leading to formation of insoluble carbonate limits their commercialization.
Other fuel cell technologies, mostly fuelled by hydrogen, include:
- High-temperature proton exchange membrane fuel cell (PEMFC) operating up to 200 °C, which is less vulnerable to catalyst poisoning by CO.
- Phosphoric acid fuel cell (PAFC) – well-developed but high-temperature and expensive, about 40% efficient, used only for stationary power generation.
- Solid oxide fuel cell (SOFC) – operating at 800-1000 °C and 60% efficiency. These run on natural gas or hydrogen but have relatively low tolerance to being turned on and off and low volumetric power density, hence are mainly used for stationary power generation (though lower-temperature versions are being developed).
- Molten carbonate fuel cell (MCFC) – high-temperature (about 650°C) with non-noble catalyst and accepting a variety of fuels, for stationary power generation due to low volumetric power density.
- Direct methanol fuel cell (DMFC) technology, fuelled by methanol not hydrogen, is practical for portable electronic uses but not favoured for automotive use at present.
A comparison of fuel cells and description of fuel cells are published by the US Department of Energy.
At present fuel cells are much more expensive to make than internal combustion engines (burning petrol/gasoline or natural gas). In the early 2000s, PEM units cost over $1000 per kilowatt, compared with $100/kW for conventional internal combustion engine. The target cost for a PEM fuel cell stack for FCEV is below €100/kW, which will require reducing the amount of platinum catalyst.
The high cost of transporting hydrogen means that production is ideally close to where it is used.
For long-haul buses and trucks, FCEV powertrains have more promise than EV battery-based systems. The initial use of hydrogen for transport is municipal bus and truck fleets, already on the road in many parts of the world. These are centrally-fuelled, so avoid the need for a retail network, and onboard storage of hydrogen is less of a problem than in cars. Buses typically use two fuel cell stacks of about 100 kW plus a small traction battery topped up by regenerative braking. They carry 30 to 50 kg of compressed hydrogen, stored in polymer-lined, fibre-wound pressure tanks at 350 bar (35 MPa). Newer fuel cell buses use only 8 to 9 kg of hydrogen per 100 km, which compares well in energy efficiency with diesel buses.
Smaller FCEVs are further from widespread commercial use than EVs and PHEVs. The IEA reported that almost 130,000 FCEVs were on the road at the end of 2025.
Fuel cell hybrid vehicles (FCHV), with an electric motor driven by the battery and the fuel cell keeping the battery topped up and giving it greater life (by being kept more fully charged) are being marketed. Battery capacity is smaller than normal battery EVs and PHEVs, but the whole fuel cell stack plus hydrogen tank is much lighter than comparable EV battery packs. Plug-in FCEVs are possible, with greater battery capacity. The main FCEV problem apart from cost is the very few refuelling stations as yet.
In 2019 Arizona-based Nikola Corporation embarked on a joint venture with IVECO in Europe to develop and market both EV trucks and fuel cell heavy trucks. Nikola began producing its Tre FCEV truck in July 2023. Nikola filed for Chapter 11 bankruptcy protection in February 2025.
In March 2021 Daimler Truck and Volvo Group formed a joint venture, cellcentric, to develop, produce and commercialize fuel cell systems, mainly for heavy-duty trucks.
The fuel cell stacks in cars have an output of about 100 kW or more. As compared with battery electric cars they usually have a better range than EVs – around 400 to 500 km – with a lower vehicle weight and much shorter refuelling times of three to five minutes. They usually carry 4 to 7 kg of hydrogen, stored in carbon fibre pressure tanks at 700 bar (70 MPa).
Honda, Toyota and Hyundai are the main car manufacturers developing FCEVs. Ford, Nissan, Renault and Mercedes have pulled back from FCEV development. See Electric Vehicles information page.
An issue with using hydrogen in fuel cells is overall energy efficiency. If a nuclear reactor generates electricity which is used for electrolysis of water and the hydrogen is compressed and used in fuel cell powered vehicle (assuming 60% efficient fuel cell), the efficiency is much lower than if the electricity is used directly in EVs and PHEVs.* However, if the hydrogen can be made by thermochemical means the efficiency doubles, and they are comparable with EV/PHEV.
* Say: 35% x 75% x 60% x 90% = 14% optimistically (reactor, electrolysis, fuel cell, motor) to:
50% x 60% x 90% = 27% for future thermochemical hydrogen
cf 35% x 90% = 31% for EV.
Apart from carbon-free production and then distribution to users, on-board storage is the principal problem for hydrogen as an automotive fuel – it is impossible to store it as simply and compactly as gasoline or LNG fuel. The options are to store it at very low temperature (cryogenically), at high pressure, or chemically as hydrides. The last is seen to have considerable potential, though refuelling a vehicle is less straightforward.
Pressurized storage is the main technology available now and this means that at 700 times atmospheric pressure (70 MPa), five times the volume is required than for an equivalent amount of petrol/gasoline. The weight penalty of a steel tank is reduced by use of carbon fibre. Earlier, the tank had been about 50 times heavier than the hydrogen it stored, now it is about 20 times as heavy, and the new target is ten times as heavy. Storage for buses can be at 35 MPa, but for cars needs to be twice that.
Fuel cells are currently being used in electric forklift trucks and this use is expected to increase steadily. They apparently cost a lot more than batteries but last twice as long (10,000 hours) and have less downtime.
Germany has a train powered by a hydrogen fuel cell, the Alstom Coradia iLint, with a range of 1600 km and in service since September 2018.
Use directly as fuel for marine transport – fuel cells and ammonia
Ballard has developed the FCwave fuel cell module for marine applications.
The International Maritime Organization (IMO) aims to reduce the carbon intensity of international shipping by at least 40% by 2030, compared with 2008 levels. Its 2023 strategy targets net-zero greenhouse gas emissions from international shipping by or around 2050. In April 2025 the IMO approved a draft Net-Zero Framework of regulations to cut emissions from ships. In October 2025 member states adjourned its adoption for one year. The annual energy demand for shipping is about 12 EJ (3300 TWh). In 2018, the international shipping industry accounted for 2.6% of the world’s carbon dioxide emissions—higher than the international aviation sector. Based on wide consultation, a Shell report showed that cryogenic hydrogen and ammonia were the two most prospective fuels for shipping, with internal combustion being the main technology available in the short-term but fuel cells being more attractive in the longer-term.
Samsung Heavy Industries is undertaking advanced research and development into ammonia- and hydrogen-powered ships, as well as developing molten salt reactors for this purpose (see Nuclear Powered Ships information page).
Stationary energy applications
Fuel cells may be used for heat or electricity, or combined heat and power.
Fuel cells using hydrogen can also be used for stand-alone small-scale stationary generating plants for remote area power supply in off-grid areas. This is particularly where higher temperature operation (e.g. of solid oxide fuel cells) and hydrogen storage may be less of a problem than in vehicles, or where hydrogen is reticulated like natural gas. Cogeneration fuel cell units for domestic power and heat were deployed in Japan under a subsidy scheme to 2012.
The market for backup power applications is increasingly important. Backup applications include both emergency power supply and also uninterruptible power supply (UPS), as well as backup for electricity from intermittent renewables.
Coal and biomass to liquid hydrocarbon fuels
Coal and biomass can be a basis for liquid hydrocarbon fuels, and has been so for nearly a century, with some dependence on hydrogen.
The Fischer-Tropsch process was originally developed in Germany in the 1920s, and based on coal provided much of the fuel for Germany during the Second World War. It then became the basis for much oil production in South Africa by Sasol, which now supplies about 30% of that country's gasoline and diesel fuel from coal and natural gas. However, it is a significant user of hydrogen, catalysing a reaction with carbon monoxide to produce liquid hydrocarbons. The hydrogen is now produced with the carbon monoxide by coal gasification, with part of the gas stream undergoing the water shift reaction (CO + H2O ⇌ CO2 + H2). Using simply black coal, 14,600 tonnes of coal produces 25,000 barrels of synfuel 'oil' (along with 25,000 tonnes of CO2).
Overall: (2n+1)H2 + nCO ⇒ CnH2n+2 + nH2O (where n is typically 10-20)
Nuclear power can be brought to bear on this in two ways. A nuclear source of hydrogen coupled with nuclear process heat would more than double the amount of liquid hydrocarbons from the coal and eliminate most CO2 emissions from the process.
Alternatively, a hybrid system uses nuclear electricity to electrolyse water for the hydrogen and the oxygen. In this case, some 4400 tonnes of coal is gasified using oxygen from the electrolysis to produce carbon monoxide which is fed to the Fischer-Tropsch plant with the hydrogen to produce 25,000 barrels of synfuel 'oil'. Very little CO2 results, and this is recycled to the gasifier.
Similarly from biomass, liquid biofuels may be produced by reacting the material with hydrogen under elevated temperatures and pressures in the presence of a catalyst. This hydrotreating technology is used by some commercial plants. Similarly the Fischer-Tropsch process may be employed in hydroprocessing wood residues for liquid fuels.
Reductant for metallurgy, especially steelmaking
A major use for metallurgical coke – essentially carbon – is in metallurgy, notably steelmaking, as a reductant. Natural gas is now well-established in the primary role of direct reduction of iron for steel, leading to several developments in hydrogen filling this role, and avoiding CO2 emissions.
The world steel industry accounts for 7-9% of direct CO2 emissions. About 69% of world steel production in 2025 was by the basic oxygen route, using iron from blast furnaces where coke is both energy source and reductant. The resulting pig iron has some carbon which is removed by oxygen injection to produce steel. About 30% of steel production is from electric arc furnaces and this proportion is expected to grow. About 7% of steel production is via direct-reduced iron (DRI) where reducing gases are passed through pelletized iron ore at high temperature (800-1200°C) to produce a porous metal sponge which is further treated in an electric arc furnace. Use of DRI is also expected to grow.
Half the energy for the arc furnace route is from electricity, lending itself to nuclear power input. Nuclear heat from high-temperature reactors has clear application to DRI. In both cases hydrogen can be the reductant.
Today the iron and steel sector accounts for 4 MtH2/yr of dedicated hydrogen production. Of the 14 MtH2/yr it produces as a by-product in hydrogen-containing gases, it consumes about 9 MtH2/yr, with the remainder exported for use in other sectors (IEA, 2019).
In northern Sweden the HYBRIT (Hydrogen Breakthrough Ironmaking Technology) project was launched in 2016 by a joint venture among Vattenfall, LKAB (iron ore producer) and SSAB (steelmaker). In 2020 LKAB announced that it was starting to produce direct-reduced ‘sponge iron’ (DRI) using hydrogen. It planned to scale this up in a demonstration plant requiring 0.25 GW of electrolyser capacity. An investment decision was due in early 2025, but LKAB deferred it without setting a new schedule. By 2040 full-scale production using HYBRIT would require 10 GW of electrolysers. In September 2021 SSAB produced its first slab of steel from DRI with hydrogen used as reductant. (LKAB production equates to 18 Mt steel, which would account for 28 Mt CO2 if produced through blast furnaces.)
At Boden in northern Sweden, H2 Green Steel (now Stegra) is building a plant intended eventually to produce 5 million tonnes of green steel per year. In mid-2026 its start-up timetable was under review. In October 2026 it was reported to need further funding to complete construction. The hydrogen will come from an 800 MW electrolyser. Some 25 TWh/yr of electricity for that will come from hydro and wind sources. An electric arc furnace will finish the process.
In June 2021 Rosatom signed an agreement with Metalloinvest, a major Russian steel maker, and Air Liquide to assess technical and commercial aspects of hydrogen production at the company’s steelworks in the Belgorod and Kursk regions. Both electrolysis and steam methane reforming with carbon capture are to be considered. Metalloinvest expects its plants to consume up to 150,000 tonnes of hydrogen per annum. It aims to upgrade its plant so that hydrogen initially comprises 30% of reducing gases.
Chemical feedstock
Beyond ammonia synthesis and methanol production, hydrogen is used in some chemical processes.
Storing and transporting hydrogen
As hydrogen gas or liquid
The low volumetric energy density of hydrogen gas poses a problem for transport and storage – 90g hydrogen occupies one cubic metre at standard temperature and pressure (STP), so one kilogram of hydrogen occupies 11.1 m3 at STP. Also, due to its small molecular size, it leaks more readily than natural gas. It is also readily flammable.
For stationary storage or portable storage in vehicles hydrogen is compressed, which adds little to its cost. Compression to 35 MPa requires about 4.4 kWh/kgH2 and gives 23 kg/m3H2. Large-scale storage can be cryogenic, as liquid, or underground in salt caverns.
In Europe, with 1.7 million kilometres of gas transmission and reticulation, Hydrogen Europe estimates that 50,000 km of natural gas pipelines can be converted to hydrogen pipelines at a cost of €25 billion. The European Hydrogen Backbone (EHB) initiative was launched in mid-2020 and by April 2021 the project had been joined by 23 system operators across 21 countries to create a network of almost 40,000 km by 2040, 69% of which would be based on existing gas pipelines. Its April 2022 update proposed about 53,000 km by 2040, covering 28 countries.
In October 2024 Germany’s Federal Network Agency approved a 9,040 km hydrogen core network, about 60% of it converted from natural gas pipelines.
In the Netherlands, a similar programme has been proposed that would cost €5-6 billion, one-quarter of the cost of building a new dedicated hydrogen pipeline.
For storage or long-distance transport, hydrogen can be liquefied cryogenically, but the boiling point is very low: minus 253°C. This compares with LNG at minus 163°C and ammonia at minus 33°C, so requires better insulation. The density of liquid hydrogen is about 71 kg/m3 (8.52 MJ/L) and up to 13 kWh/kgH2 (about 47 MJ/kgH2) is required to liquefy it. The extra cost is likely to be over $2/kg.
For import and export, sea ports are considering necessary facilities for hydrogen, and Rotterdam with distributor Gasunie plan to jointly construct and operate a hydrogen pipeline linking Rotterdam port as a hydrogen hub to the national hydrogen network being developed by Gasunie.
Japan has built a liquid hydrogen tanker, the Suiso Frontier, for sea trade. It is based at Kobe.
As hydrogen derivative: ammonia
Ammonia (NH3) makes a good carrier of hydrogen, or means of long-term storage. It is a key part of the hydrogen picture, for storing it or moving it over long distance at much lower cost than for hydrogen itself.
Ammonia will be made by some refinement of the Haber Bosch process, then dissociated to release the hydrogen, requiring about 8 kWh/kgH2. Conversion to and from ammonia is likely to add about $1/kg to the hydrogen production cost.
Ammonia has thermal properties similar to propane, is easy to cool and compress into liquid form for transport and storage (boiling point minus 33°C), and has an energy density that is competitive with carbon-based fossil fuels. It contains 17.7% hydrogen by weight. Ammonia’s energy density of 18.6 MJ/kg* is comparable to that of compressed natural gas and methanol, but about half that of petrol/gasoline, diesel fuel and liquefied petroleum gas (LPG).
* 4.32 kWh/L or 5.18 kWh/kg. On this basis ammonia quantities may be quoted in GWh, PWh, etc. as with hydrogen.
Ammonia is seen as a large-scale solution to the problems in storage and movement of hydrogen beyond pipelines. According to the source of hydrogen, the ammonia may be ‘green’, ‘blue’ or ‘grey’. Already, some 17-20 million tonnes of ammonia is traded internationally by sea each year, so handling is well-established. It can be stored and moved at pressures of 800-1000 kPa, similar to propane, or in refrigerated tanks.
After storage or transport, the ammonia can be dissociated or ‘cracked’ back into hydrogen and nitrogen by thermal catalytic decomposition or electro-oxidation. In November 2025 Air Liquide started up an industrial-scale ammonia cracking pilot unit at the Port of Antwerp-Bruges, able to convert 30 tonnes of ammonia per day. Alkaline fuel cells use impure hydrogen (c. 90%) cracked from ammonia, but PEM fuel cells in road vehicles require hydrogen of at least 99.97% purity, with limits on individual contaminants. Ammonia may also be used directly in fuel cells or marine internal combustion engines, or blended with petrol/gasoline.
As metal hydride
Storage as hydrides has potential and one promising hydride storage system utilizes sodium borohydride (NaBH4) as the energy carrier, with high energy density. The NaBH4 is catalysed to yield its hydrogen, leaving a borate (NaBO2) to be reprocessed.
Liquid organic hydrogen carriers (LOHC)
Hydrogen can be combined with toluene to form methylcyclohexane (MCH) which can be stored and transported at ambient temperature and pressure. Japanese companies led by Chiyoda and Mitsubishi are investigating the economic feasibility of this. LOHC seems most suited to long-distance transport of hydrogen.
Notes & references
References
1. Hydrogen Council, McKinsey & Company, Hydrogen Insights – A perspective on hydrogen investment, market development and cost competitiveness, (February 2021) [Back]
General sources
Alternative Fuels Data Center, US Department of Energy, webpage on Renewable Hydrocarbon Biofuels
Ammonia Energy Association website
US Department of Energy's Hydrogen and Fuel Cell Technologies Office (HFTO) website
Tom Koppel and Jay Reynolds, A Fuel Cell Primer: The Promise and the Pitfalls (2000)
Benjamin Russ and Bob Buckingham, Sulfur Iodine Process Summary for the Hydrogen Technology Down-Selection: Process Performance Package, General Atomics (June 2009)
Hydrogen Production Using Nuclear Energy, IAEA Nuclear Energy Series No. NP-T-4.2, International Atomic Energy Agency (March 2013)
Hydrogen mobility gets a boost in Europe, Engerati (July 2016)
Grigorii Soloveichik, Advanced Research Projects Agency - Energy (ARPA-E), US Department of Energy, Ammonia as Virtual Hydrogen Carrier, presented at the H2@Scale Workshop held on 16-17 November 2016 in Golden, Colorado, USA
National Hydrogen Roadmap – Pathways to an economically sustainable hydrogen industry in Australia, Commonwealth Scientific and Industrial Research Organisation (2018)
The Future of Hydrogen: Seizing today’s opportunities, Report prepared by the IEA for the G20, Japan, International Energy Agency (June 2019)
International Energy Agency webpage on Hydrogen
Zero-Carbon Hydrogen: An Essential Climate Mitigation Option – Nuclear Energy’s Potential Role, Energy Options Network (July 2020)
Yong-Liang Por, Great Expectations – Asia, Australia and Europe Leading Emerging Green Hydrogen Economy, but Project Delays Likely, Institute for Energy Economics and Financial Analysis (August 2020)
Sebastian Timmerberg et al., Hydrogen and hydrogen-derived fuels through methane decomposition of natural gas – GHG emissions and costs, Energy Conversion and Management: X, Volume 7, 100043 (September 2020)
Energy Technology Perspectives 2020, International Energy Agency (September 2020, revised February 2021)
Global Hydrogen Review 2021, International Energy Agency (October 2021)
Eric Ingersoll and Kirsty Gogan, Missing Link to a Livable Climate – how hydrogen-enabled synthetic fuels can help deliver the Paris goals, LucidCatalyst (September 2020)
Making the Hydrogen Economy Possible – Accelerating Clean Hydrogen in an Electrified Economy, Energy Transitions Commission (April 2021)
Roxanne Pinsky et al., Comparative review of hydrogen production technologies for nuclear hybrid energy systems, Progress in Nuclear Energy, Volume 123 (May 2020)
Decarbonising hydrogen in a net zero economy, Aurora Energy Research (September 2021)